
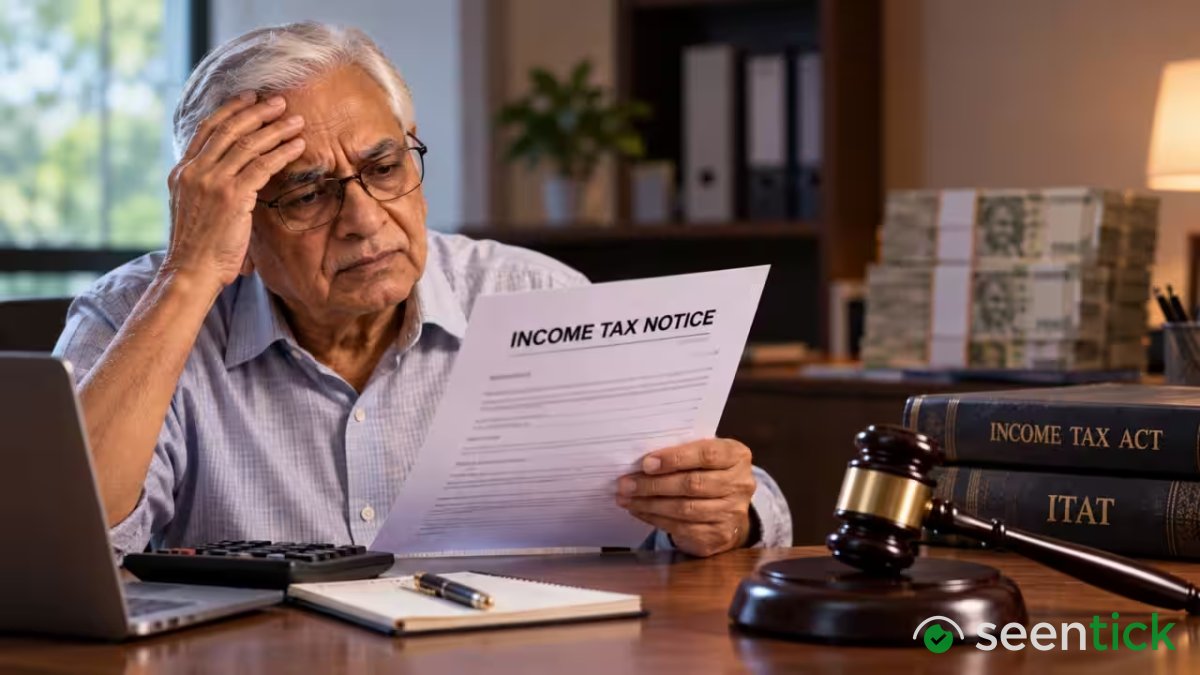
Retired Teacher's Rs 1.33-Crore Deposit Sparks ITAT Ruling on Reassessment Notice Timing
Key Highlights
- A cash deposit of Rs 13 lakh in a savings bank account fell within the category of cash deposits of Rs 10 lakh or more.
- The ITAT Bangalore ruled that the Section 148 notice was issued after the prescribed period had already expired.
- The tribunal quashed the Section 148 notice and the reassessment order passed under Section 147, allowing the assessee's appeal.
A former Mysore school teacher has been embroiled in a contentious tax dispute after his bank accounts. Which accumulated Rs 1.33 crore, were flagged by the Central Board of Direct Taxes as part of its risk management strategy. The Income Tax Department has initiated reassessment proceedings against him, citing an outstanding ITR for the relevant fiscal year.
Notably, the department's investigation reveals a significant cash influx without corresponding records of income earned during this period.
Following a series of cash deposits, the department launched an investigation into the senior citizen's unreported income for the 2015-16 fiscal year. The Assessing Officer served the individual with a Section 148 notice. Mandating them to file their tax return within 30 days of receipt.
A cash deposit of Rs 13 lakh in a savings bank account fell within the category of cash deposits of Rs 10 lakh or more. A cash deposit of Rs 60 lakh, also reported under the same category, was another transaction flagged by the department.
Bank interest: Rs 12,701 recorded under "Interest other than Interest on Securities", Section 194A.
Also Read: Rooftop solar market has potential to reach 132 GW by 2030: ISMA
The first notice was issued to the senior citizen under Section 148A(b) on March 26, 2022. However, the Section 148 notice in this case was issued on April 26, 2022, 26 days after the limitation period had ended.
The SMC Bench of the ITAT heard the senior citizen's appeal on April 15, 2026. Later, passed its order in his favour on July 10, 2026. The tribunal quashed the Section 148 notice and the reassessment order passed under Section 147, allowing the assessee's appeal.
What's Your Reaction?
 Like
 Dislike
 Love
 Funny
1
 Wow
2
 Sad
 Angry
1
I write about the forces shaping business and the global economy, from startup growth and changing markets to international trade and policy. My work focuses on breaking down complex developments into clear, practical insights and understanding what they could mean for businesses, investors, and the wider economy.





Comments (0)