
UPI vs Credit Cards: The Value-Back Debate
Key Highlights
- UPI offers convenience and simplicity, but credit cards provide cashback and rewards.
- MDR on higher-value UPI transactions adds another dimension to the comparison.
- Consumers should consider the net economics of each payment method.
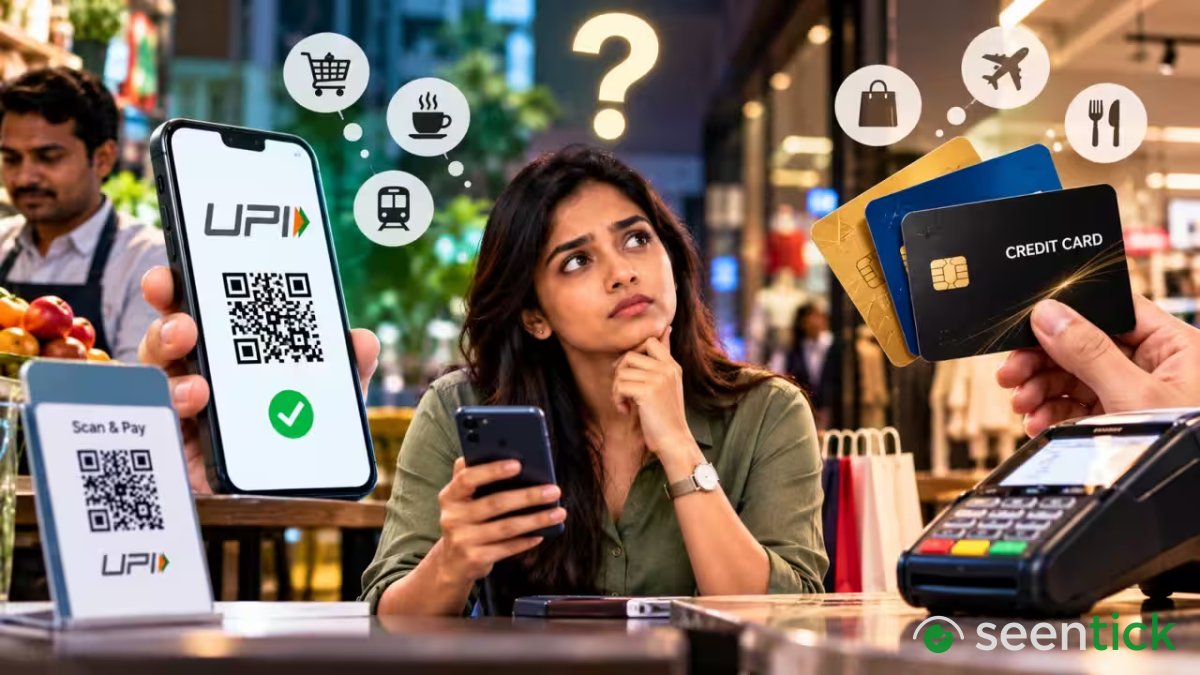
As the digital payment ecosystem continues to evolve, consumers are grappling with the question of which option – UPI or credit cards – provides the most compelling value proposition for their transactions. A closer examination of the economics of each method is now warranted, particularly with the introduction of MDR on higher-value UPI transactions.
Experts agree that UPI provides convenience and simplicity, but credit cards offer cashback, rewards, and additional perks. However, the impact of MDR on consumers will depend on how the ecosystem responds to this new development.
For instance, a Rs. 50,000 transaction on a card offering 5% cashback could potentially yield Rs. 2,500 back, subject to the card's terms, redemption value, and applicable caps.
In contrast, paying the same amount through UPI and the merchant passing on the entire MDR cost of 0.4% could result in an additional Rs. 200 being paid, with no additional benefits.
Read More: GST Collections Reach New Highs, India's Next-Phase Growth Plans Take Shape
The discussion around MDR on higher-value UPI transactions adds another layer to this comparison. MDR represents a cost associated with accepting a digital payment. The relative economics for merchants can vary across payment instruments and transaction types.
Consumers should look at the frequency of spending and the cumulative rewards generated over time, according to [CEO of Paisabazaar]. The value of small individual transactions can add up to significant rewards when they form a large portion of monthly expenditure.
As consumers continue to handling payment options, a key takeaway emerges: there is no one-size-fits-all solution for finding the most valuable payment method. Rather, the focus should shift from convenience and transaction value to a more nuanced evaluation of the net economics at play.
This allows individuals to select the payment instrument that best aligns with their unique spending habits and priorities.
The introduction of MDR on higher-value UPI transactions has significant implications for consumers and merchants alike. To make informed decisions, it is essential to consider the net economics of each payment method, taking into account factors such as transaction frequency, rewards, and fees.
Also Read: TCS Says Trump's PERM Suspension Won't Affect US Hiring Plans
Ultimately, the choice between UPI and credit cards depends on individual circumstances and priorities. By understanding the economics of each payment method, consumers can make informed decisions that align with their unique needs and spending habits.
The digital payment ecosystem is constantly evolving, with new developments and innovations emerging regularly. As consumers navigate this complex landscape, it is essential to stay informed and up-to-date on the latest trends and developments.
Experts agree that a more nuanced approach to evaluating payment options is necessary. One that takes into account the unique needs and circumstances of each individual. By doing so, consumers can make informed decisions that maximize their rewards and minimize their costs.
What's Your Reaction?
 Like
1
 Dislike
 Love
 Funny
 Wow
 Sad
 Angry
3
I write about the forces shaping business and the global economy, from startup growth and changing markets to international trade and policy. My work focuses on breaking down complex developments into clear, practical insights and understanding what they could mean for businesses, investors, and the wider economy.


Comments (0)