
Man Wins Tax Case After Tribunal Verifies Commercial Nature of Dhakoli, Zirakpur Property
Key Highlights
- Man sells ancestral land for Rs 8 crore and claims LTCG exemption.
- ITAT Chandigarh rules substantially in his favour on both questions.
- Tribunal permits Section 54B deduction to the extent of qualifying investment.
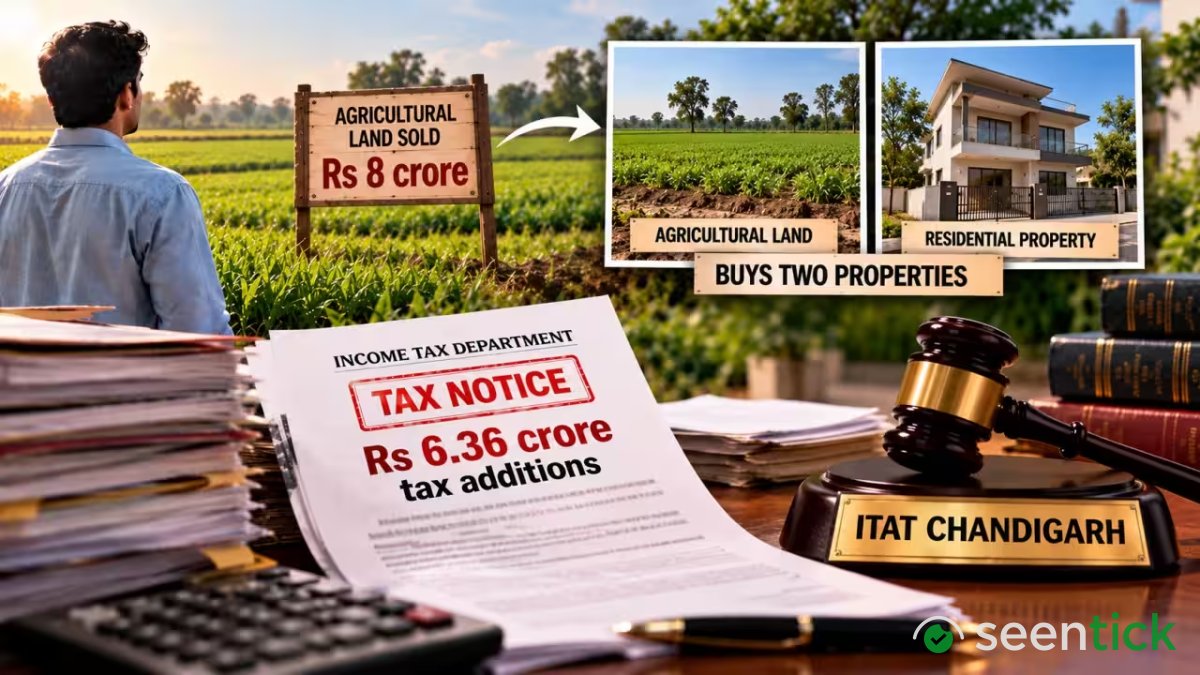
A Panchkula resident, identified only as Heathen, had sold his family's ancestral farmland for a substantial Rs 8 crore in 2017, taking advantage of long-term capital gains exemption. But his claims under Section 54B and Section 54F were rejected, prompting a tax assessment and a formal notice.
Heathen subsequently appealed the decision to the Commissioner of Income Tax (Appeals), where he secured a favorable ruling on September 1, 2026. This comes after a substantial victory for him at the Income Tax Appellate Tribunal (ITAT) Chandigarh.
Under the Income-tax Act's 54B provision, eligible taxpayers can claim a full exemption from long-term capital gains tax when selling agricultural land that was used for farming over the preceding two years. To qualify, the gains must be reinvested in another agricultural property within a two-year window following the initial sale.
Read More: Bank Fined Rs 10,000 Over Delayed Funds to Deceased Customer
This ensures a seamless transition and supporting sustainable agricultural practices.
A tribunal ruling has allowed a Section 54B deduction for a qualifying investment. With the amount tied to the value of property purchased, as documented in purchase deeds and supporting records.
The Chandigarh ITAT case highlights the importance of considering a property's inherent nature when evaluating eligibility for capital gains tax exemptions. With evidence playing a important step in this assessment.
A local farmer sold his rural estate in a village to a buyer for a whopping Rs 8 crore in 2017. This marked a significant milestone in his business ventures. The deal also helped the purchase of two adjacent properties in Chhat and Sanoli villages.
Also Read: Delhi Traffic Signals Get a Brain: Rs 1,789.52-Crore ITMS to Optimize Commute
This allows him to capitalize on long-term capital gains tax benefits under Sections 54B and 54F. Additionally, the entrepreneur owned a restaurant in Dhakoli, which doubled as his office space.
Rs 8 crore, Rs 7.73 crore, Rs 2.64 crore, Rs 3.73 crore, Rs 6.36 crore, Rs 80 lakh, Rs 45 lakh, 2017, 2026, 1961, 2025, 2018, September 1, 2026.
Rs 2.64 crore under Section 54F and Rs 3.73 crore under Section 54B were disallowed by the Assessing Officer. The tribunal deleted the disallowance of Rs 2.64 crore under Section 54F, subject to fulfilment of the remaining statutory requirements.
What's Your Reaction?
 Like
1
 Dislike
 Love
 Funny
 Wow
3
 Sad
 Angry
I write about the forces shaping business and the global economy, from startup growth and changing markets to international trade and policy. My work focuses on breaking down complex developments into clear, practical insights and understanding what they could mean for businesses, investors, and the wider economy.


Comments (0)