
Farmer Wins ITAT Case, Cash Deposits Ruled as Agricultural Income
Key Highlights
- Ramachandrababu, a farmer from Bengaluru, successfully challenged an income tax notice over large cash deposits in his bank account.
- The ITAT Bangalore ruled in his favour, concluding that the cash deposits were supported by agricultural income.
- The tribunal accepted the farmer's explanation, rejecting the tax department's objections.
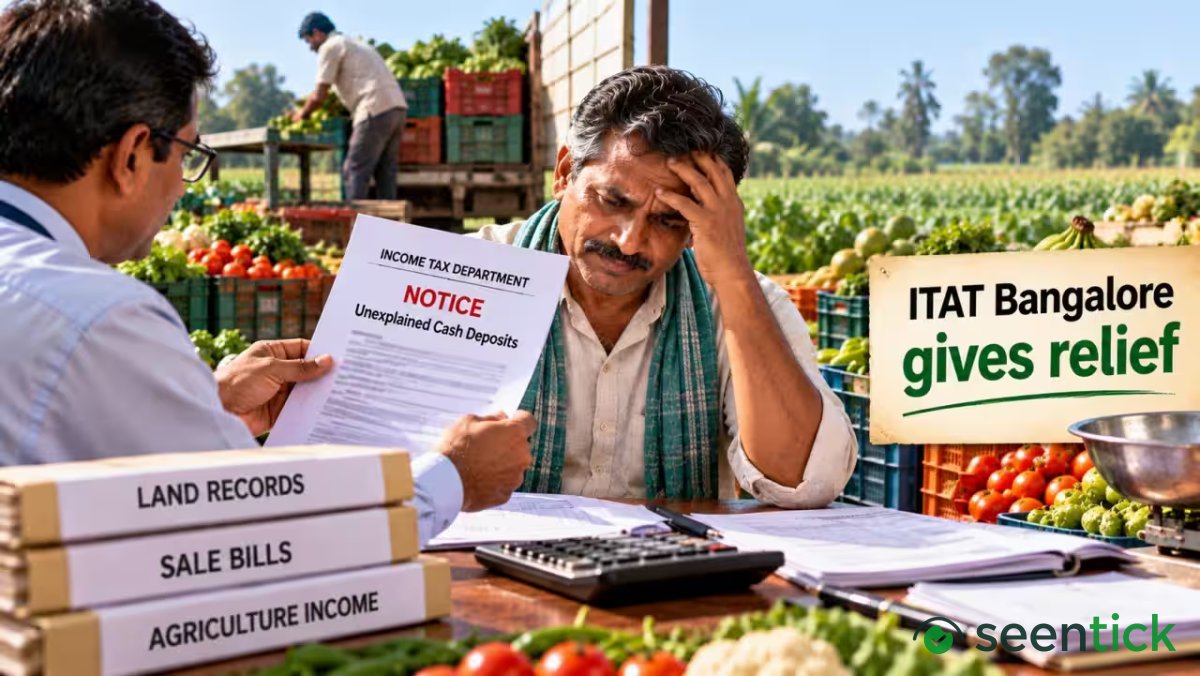
Ramachandrababu, a farmer from Bengaluru, successfully challenged an income tax notice over large cash deposits in his bank account, with the Income Tax Appellate Tribunal (ITAT), Bangalore, ruling in his favour on August 28, 2026. The farmer had grown fruits and vegetables on his four-acre agricultural land. Which he sold for cash at an Agricultural Produce Market Committee (APMC) yard.
The farmer had furnished copies of his land records. Bills documenting the sales at the APMC yard, and bank statements to substantiate his account. He maintained that the deposits were money earned from agricultural activities.
Which he claimed were supported by his land records and sales data.
The department suspected a mismatch between Ramachandrababu's income tax return and his bank transactions. Which raised concerns about the legitimacy of the cash deposits.
Read More: RBI Governor Sanjay Malhotra Downplays Impact of MDR Fee on UPI Transactions
The farmer had provided documentation to support his claims. This includes land records, sales bills, and bank statements, which he believed demonstrated that the deposits were earned from agricultural activities.
At a recent hearing, the Income Tax Appellate Tribunal in, Bangalore noted. that tax officials had raised concerns over two key areas: the omission of agricultural income from the farmer's tax returns and the ambiguity surrounding the accompanying documentation.
The tribunal considered the records relating to Ramachandrababu's agricultural land. This includes the RTC and pahani records. As well as the monthly summaries of sale bills and individual bills for agricultural produce sold through the APMC market.
Analysis of the documents revealed that Ramachandrababu owned the land in question and that the RTC records. Maintained by the Karnataka state authorities, did not provide conclusive evidence of the crops grown on his land.
The tribunal noted that the absence of details about the crops in the RTC records did not necessarily imply that Ramachandrababu had not grown any agricultural produce.
The ITAT Bangalore has expressed skepticism about the feasibility of maintaining intricate records for small-scale agricultural operations. Citing the impracticality of such demands for those engaged in such activities.
Also Read: RBI Makes Account Aggregators Interoperable, Facilitating Easier Access to Financial Info
After considering the taxpayer's submissions and the documents he had furnished, the ITAT Bangalore accepted his explanation and concluded that the cash deposits were supported by agricultural income and could not be classified as unexplained money under Section 69A.
Experts say that Ramachandrababu's case sets a precedent for farmers who may face similar challenges in the future.
Grant Thornton Bharat Partner and Global People Solutions Leader Akhil, Chandna noted. that the landowner was able to establish the origin of the cash deposited in his bank account. Which helped to resolve the dispute.
The ITAT Bangalore's ruling is a significant development in the area of tax dispute resolution. And it is likely to have implications for farmers and taxpayers across the country.
What's Your Reaction?
 Like
 Dislike
 Love
 Funny
 Wow
2
 Sad
1
 Angry
1
I write about the forces shaping business and the global economy, from startup growth and changing markets to international trade and policy. My work focuses on breaking down complex developments into clear, practical insights and understanding what they could mean for businesses, investors, and the wider economy.


Comments (0)